Key Notes
- Adena Friedman says tokenization could free tens of billions tied up in collateral by making assets and payments easier to move.
- Vanguard and Wellington have tested tokenized fund shares on Canton through Nasdaq Calypso, with legal agreements recognizing the assets as eligible collateral.
- Nasdaq’s wider work connects trading, risk and surveillance, while its issuer-centered equity token design aims to preserve ownership and governance rights.
Nasdaq CEO Adena Friedman says blockchain-based tokenization could free tens of billions of dollars tied up in collateral, giving financial institutions more flexibility to move capital across markets.
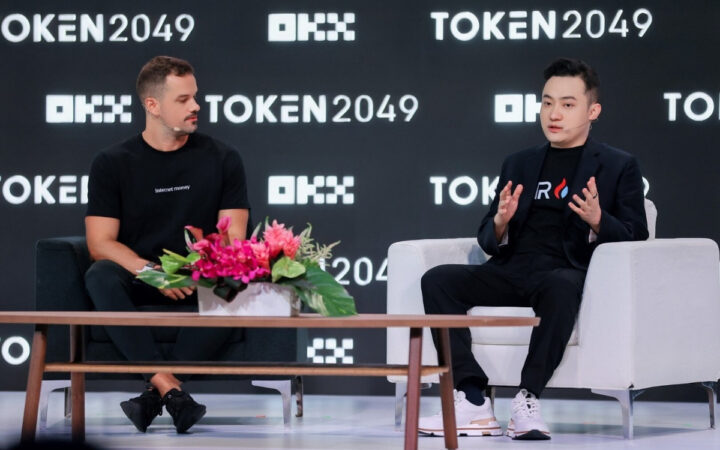
Speaking to CNBC’s Joanna Ossinger at TOKEN2049 in Singapore on October 8, Friedman said tokenizing Treasuries, equities, money market funds and payments could make the financial system’s collateral more mobile.
“If you tokenize all those instruments along with the flow of money, then the collateral becomes very fluid,” she said.
Why Collateral Mobility Matters
Collateral is an asset pledged to secure an obligation, such as a loan or a derivatives position. The operational challenge is ensuring that an eligible asset reaches the right counterparty when needed, with its ownership and value correctly recorded.
Nasdaq and the ValueExchange’s research illustrates the friction involved. Their survey of 203 market participants found that 70% reported settlement matching and delivery problems daily, while the average firm maintained roughly 7% excess collateral as protection against potential failures.
The survey estimated that about a quarter of total collateral usage earned no return for its owner. Its respondents included investment banks, custodians, prime brokers, asset managers and central counterparties.
These findings help explain the commercial argument for tokenization: more reliable transfers could reduce the need for precautionary buffers and make existing assets available for other uses. That would improve capital efficiency rather than create new capital simply by issuing a token.
Vanguard and Wellington Have Tested the Workflow
Nasdaq’s September 14 update provides a practical example. Vanguard and Wellington Management completed initial tokenized collateral test trades on the Canton Network, using Nasdaq Calypso to manage the process.
The assets were tokenized money market fund shares, with each token representing a legally enforceable interest in the underlying fund. The parties amended their bilateral agreements to recognize those tokens as eligible collateral.
Calypso handled eligibility checks and margin calls, followed by an onchain transfer between the parties’ wallets. Nasdaq said settlement occurred in real time, collateral inventories updated automatically and no manual intervention was needed at settlement.
The exercise demonstrated that tokenized instruments could fit into established institutional workflows. It remained a set of test trades, rather than evidence that the entire collateral market had moved onto blockchain infrastructure.
The legal agreements were part of the implementation. A technically transferable token alone would not establish that a receiving institution must accept it as security for an obligation.
Connecting Trading, Risk and Compliance
Nasdaq has also been building connections between conventional finance and digital asset systems. Its March 23 partnership with Talos was announced to integrate digital asset infrastructure with Calypso and Nasdaq Trade Surveillance.
Talos supplies portfolio, valuation and execution technology for digital assets. Calypso manages risk, margin and collateral across mainstream markets. The planned integration aims to let institutions handle onchain and off-chain exposures within a coordinated operating environment.
The surveillance component addresses a separate requirement: monitoring trading for potential abuse. Nasdaq’s announcement described alerts for activities including spoofing, wash trading and manipulation across markets.
That work shows why tokenization involves more than recording ownership on a blockchain. Institutions also need systems that determine what they hold, what obligations those assets secure and whether activity complies with the rules governing their business.
Tokenized Shares Still Need Shareholder Rights
Nasdaq’s earlier equity framework, outlined in March, puts issuers at the center of tokenized share ownership. Its design links blockchain records with official share registers and seeks to preserve the legal equivalence of the token and the underlying security.
The company said the framework would involve issuers, transfer agents, regulators and market infrastructure providers, with the program expected to become operational in 2027. That timetable describes the equity initiative, rather than a deadline for realizing Friedman’s wider capital-efficiency forecast.
CoinScreamer’s coverage of Securitize Stocks examined a different structure: share-backed security entitlements, whose holders are not automatically registered shareholders. The comparison highlights why investors must examine a token’s legal rights as well as its trading technology.
24/7 Markets Require Continuous Operations
Friedman also said round-the-clock markets would require continuous risk and collateral management. Nasdaq’s AI agents initially offer recommendations, with more direct actions a possible later step. She cautioned that some assets lack the liquidity needed for 24/7 trading.
Settlement technology is another part of that transition. CoinScreamer recently covered Solana DvP, which links delivery of a tokenized asset to its payment. Its atomic exchange mechanism does not itself provide an order book, investor screening or price discovery.
Nasdaq’s research identifies implementation costs, duplicated systems and expanded staffing for continuous margin management as barriers to adoption. The opportunity therefore depends on institutions connecting legal agreements, operating systems and settlement networks, alongside the tokens themselves.
Disclaimer: CoinScreamer is an independent media brand owned and operated by NuvexMedia LLC, publishing news, research, and market insights on digital assets and related technologies. NuvexMedia LLC invests in and collaborates with companies across the digital asset, blockchain, and technology sectors. These relationships do not influence CoinScreamer’s editorial coverage, and the publication maintains full editorial independence to provide accurate, timely, and objective information. © 2025 NuvexMedia LLC. All rights reserved. This content is for informational purposes only and should not be considered legal, tax, investment, financial, or other professional advice.